
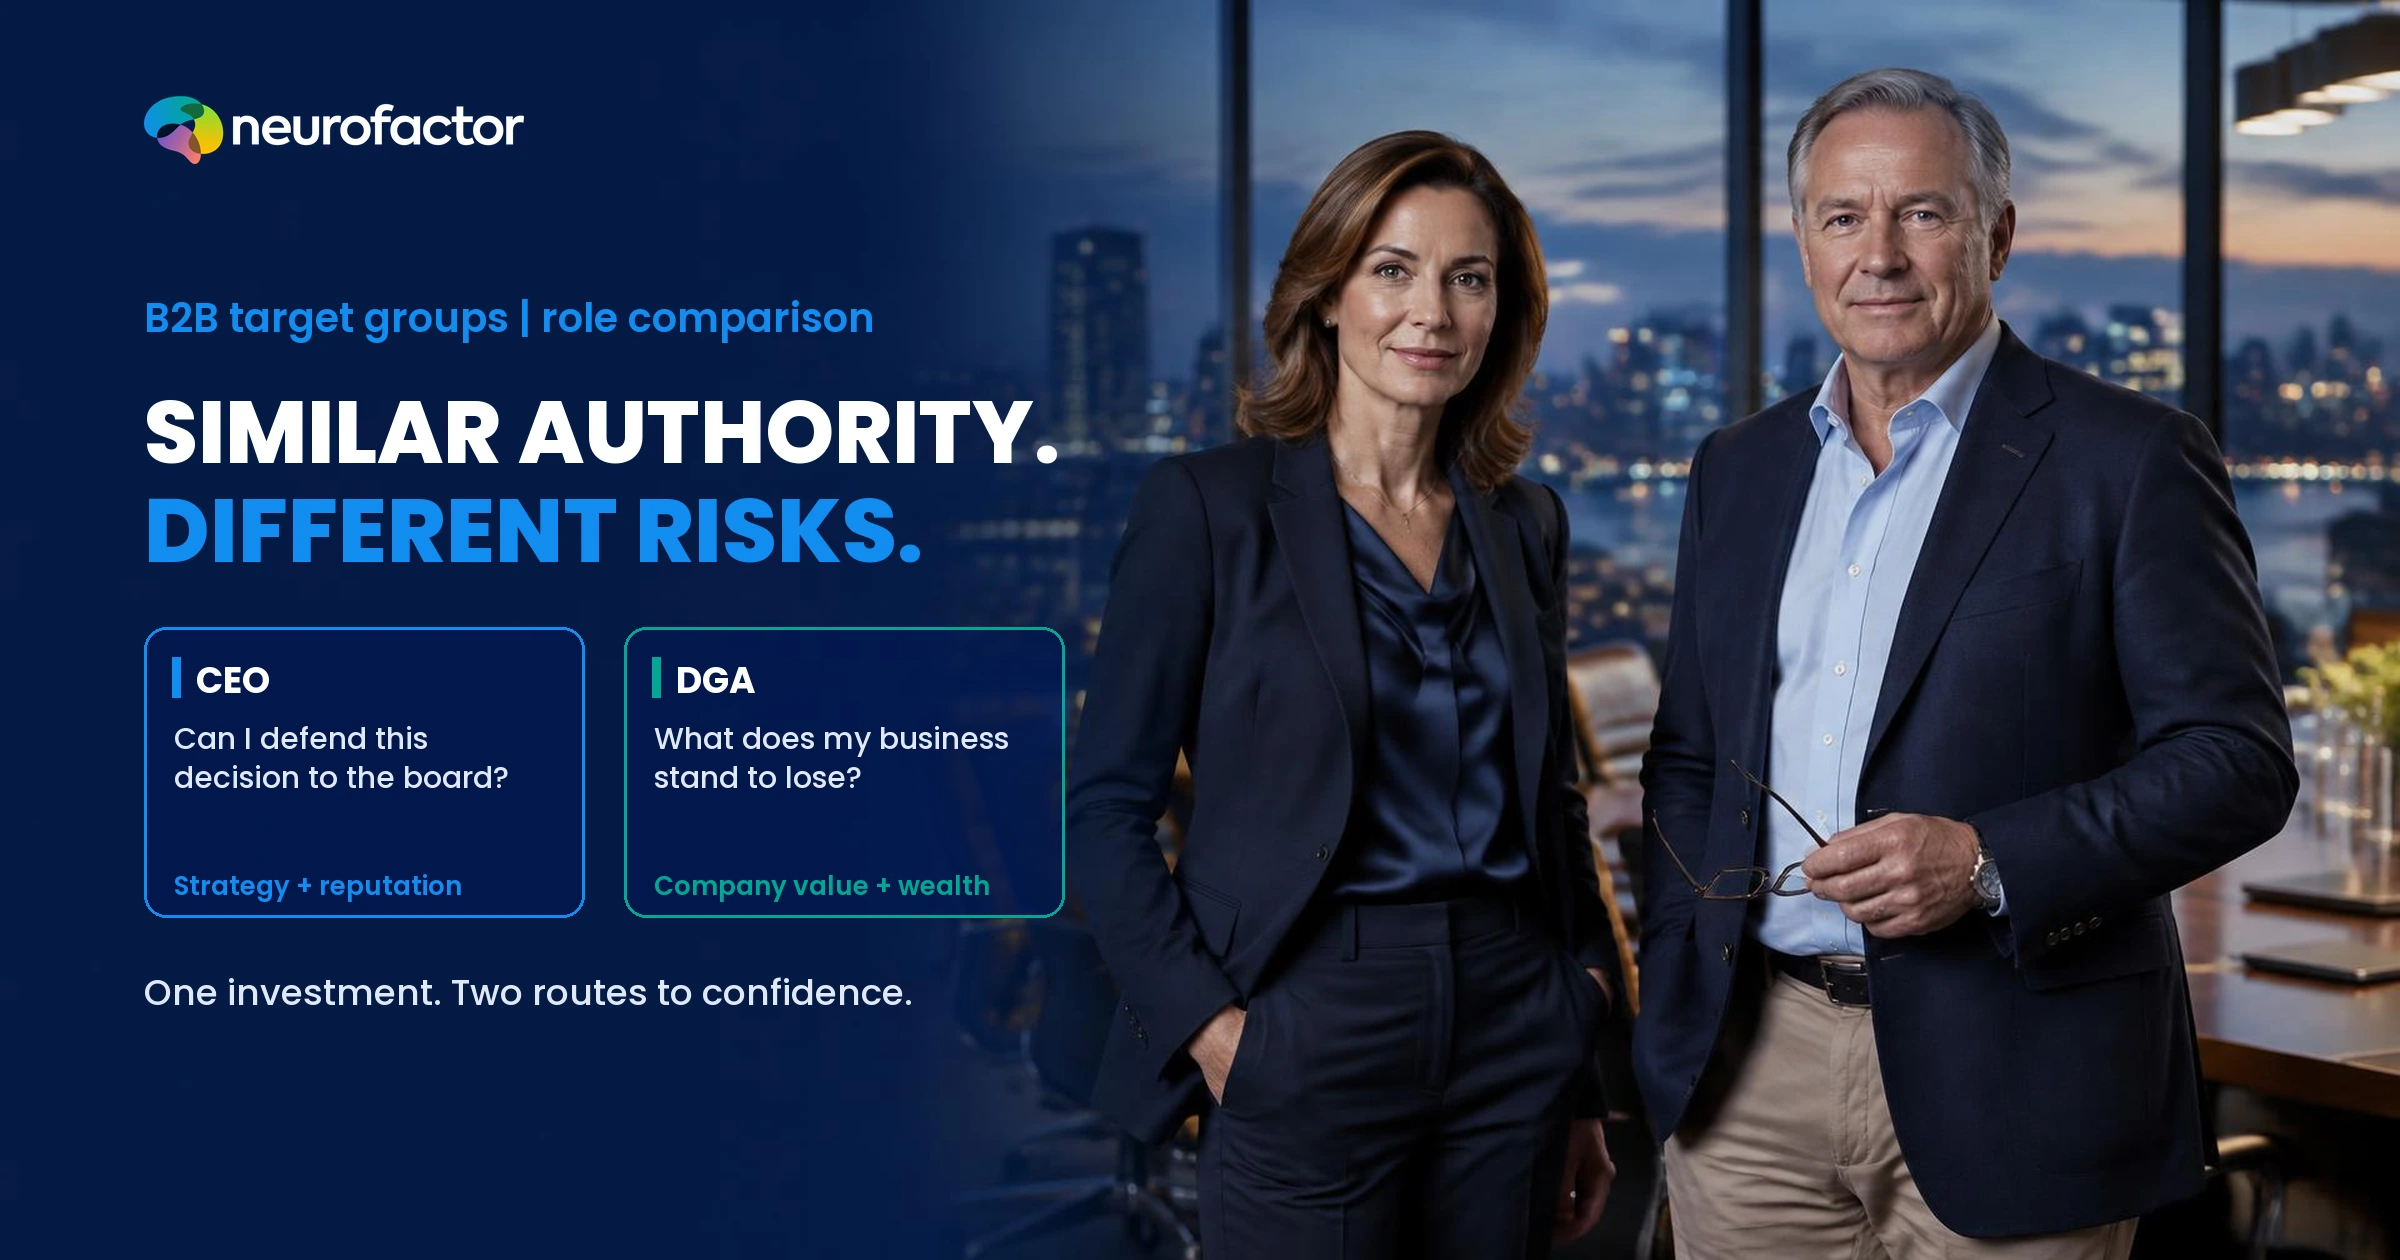
CEO vs DGA: similar decision power, very different relationship with risk
A provider pitches the same strategic improvement programme to two people with the authority to set direction. The CEO asks how the proposal advances strategy and how it can be explained to the board. The DGA, a Dutch director-major shareholder, wants to know what remains after costs, what could go wrong and how the decision affects the business they own. Both can influence the decision. Their exposure to the consequences is not identical.
The difference is not that CEOs are rational while owners act emotionally. Both assess commercial facts and personal responsibility. The CEO must protect the organisation's course and reputation in front of stakeholders. The owner-director must also consider company valuation, wealth at risk and control of the business built over time. That calls for two evidence routes, not necessarily two different products.
One offer, two very different conversations
A consultant offers an organisational programme linking decision data, risk oversight and execution. The opening to the CEO might be: this will help deliver your strategy while keeping implementation and reputational exposure manageable. The opening to the owner-director is different: here is how we will investigate potential value creation, cost and avoidable financial exposure. The service has not changed, but the reason to trust the recommendation has.
Words such as transformation, growth and resilience remain too broad until the provider connects them to the decision maker's role. A CEO may need the management team and supervisory board to support a difficult change. A DGA needs a clear view of implications for enterprise value, expenditure and freedom to keep steering the company. Relevance begins with the buyer's responsibility rather than a feature list.
What the original Neurofactor profiles actually say
The comparison below uses the original profile fields directly. Primary fear, first objections, expected evidence and preferred contact channel have not been reverse-engineered from BIS, BAS or k. They come from the broad function profiles and give a starting point for commercial preparation, not a personality test.
The CEO profile describes an appointed executive leading a larger organisation and reporting to shareholders or supervisory bodies. The DGA profile describes an owner who is also a director, often operating through a holding structure. These roles therefore represent different organisational settings as well as different job titles. A founder who becomes a CEO, or an owner who works with a supervisory board, may share characteristics of both.
| Profile field | CEO | DGA |
|---|---|---|
| Role context | Appointed executive; larger organisation with stakeholders | Owner-director; business value and personal economic exposure |
| Main problem | Limited direct visibility into organisation and market | Uncertainty about protection and structure of business and wealth |
| Primary fear | Damage to organisational reputation or own position | Loss of wealth or company value |
| Initial objections | Too operational; not strategic; reputational exposure | I already have an accountant and adviser |
| Evidence | Recognised organisations; senior counterparts; board-level track record | Numerical analysis; comparable companies; specialist authority |
| Preferred introduction | Supervisory board member, fellow CEO or trusted adviser | Accountant or adviser, then a private substantive discussion |
| BIS / BAS / k | 6 / 7 / 0.10 | 7 / 6 / 0.10 |
Why equal decision power is a misleading shortcut
Both a CEO and an owner-director may be able to sponsor a major decision. Neither necessarily signs every contract independently. A CEO operates within mandate, corporate governance, budgets and stakeholder expectations. A DGA may have considerable discretion but can still face co-owners, lender covenants, legal duties and trusted professional advisers.
What matters to an investment decision is not authority in isolation, but the cost of being wrong. Can an initiative harm institutional credibility? Might it affect the value of a company someone owns? Could it constrain their future freedom of action? These questions shape the evidence a credible supplier must provide. Check the actual decision process before treating either label as a universal buyer type.
CEO: reputational exposure can outweigh an attractive promise
The CEO card identifies insufficient visibility into what is really happening in the organisation and market as a central problem. Information can be filtered through management layers and the executive's agenda is partly set by others. Slow transformations and advisers who deliver presentations without helping change happen create further frustration. The primary fear is a decision that damages the organisation's reputation or the CEO's own standing.
That helps explain why an overly detailed technical pitch may fail. The supplier must show how the proposal advances strategy, strengthens execution and remains defensible if outcomes disappoint. An innovative tool is not yet a board-level outcome. This is not a claim that CEOs never care about operational detail. It is a reminder to place detail within the strategic question the executive must answer.
DGA: a poor decision can erode business and personal value
The DGA card describes uncertainty about whether the company and personal wealth are protected and structured well enough. Tax and legal complexity, limited time for analysis and advisers charging by the hour without clear results create pressure. Ownership brings pride in what has been built, along with concern about protecting its future.
The primary fear in this card is a decision that harms wealth or company value. A proposal cannot rely entirely on a narrative about opportunity. It should clarify the value at stake, remaining uncertainties, cash commitment and the supplier's responsibility. Acknowledging that economic exposure can be personally significant does not make the owner irrational. It identifies the actual business risk against which a recommendation will be judged.
What constitutes credible proof for the CEO?
The CEO card requests references from recognised organisations, senior-level counterparts and an established track record at board level. A credible case links the recommendation to strategic priorities and explains how execution is owned by management. Governance, decision gates, reputational downside and a response to weak results belong in that discussion.
For instance, what strategic outcome does the programme support? Who owns delivery? Which indicators will the board see, and when can the organisation revise its course? Only present outcomes that were genuinely measured or documented. A prestigious client logo without relevance to the specific situation is limited evidence. A concise board memo may be a better first proof asset than a lengthy product demonstration.
What constitutes credible proof for the owner-director?
The DGA card explicitly calls for numerical analysis, a track record with similar firms and subject-matter authority. It also expects a thorough diagnosis, clear plan and fixed fee or transparent rate. Separate potential return from verifiable costs and from assumptions about valuation. Show a downside scenario alongside the value opportunity.
The objection 'I already have an accountant and an adviser; what do you add?' is central to the source profile. The answer should not undermine the existing adviser. Specify the complementary expertise you offer, how the adviser can participate, what deliverables will be produced and how additional value will be assessed. Pricing clarity helps establish whether a proposed service adds more than another layer of advisory expense.
BIS, BAS and k: different emphases, identical k
The broad CEO profile records BIS 6, BAS 7 and k 0.10. The DGA profile records BIS 7, BAS 6 and k 0.10. The CEO card pairs concern about reputational damage with an orientation towards visible strategic opportunity. The DGA card gives relatively greater emphasis to avoiding loss and identifying opportunities with clear financial upside. These are useful framing patterns, not a prediction about an individual person's behaviour.
BIS and BAS are used here as broad indicators of sensitivity to potential threats and rewards. They are not percentages, purchase probabilities or clinical measures. k is a separate delay-discounting parameter, not a time-to-sign, deal probability or sales-cycle metric. The original cards give both roles the same k: they do not justify saying that either one consistently makes decisions sooner.
Looking ahead is not the same as valuing the future alike
The CEO profile concerns multi-year strategic priorities, quarterly and annual accountability and infrequent, high-impact purchases. The owner-director profile points to enterprise value, succession, sale and wealth structure, again in a setting where large purchases are relatively rare. Both can consider benefits and risks over several years.
But a CEO needs a longer-term initiative to remain strategically legitimate and governable. For the DGA, the question also includes whether it protects or enhances the owned business, its financing capacity and future choices. A real purchasing timetable depends on the project, shareholders, contract and available alternatives. It cannot be read from k alone.
Different first objections call for different answers
The original CEO objections are that a proposal is too operational, does not fit the strategic agenda or creates excessive reputational risk. Address these through clear strategic alignment, a senior counterpart, governance and identifiable decision checkpoints. A CEO does not need to click through every application screen to judge whether an initiative merits sponsorship.
The DGA profile raises a different objection: existing accountants and advisers already cover the territory. Show exactly what your offer adds, where specialist responsibilities begin and end, how results are reviewed and what the engagement will cost. Repeating that you are a trusted strategic partner is not evidence of incremental value.
Illustrative case: a strategic resilience programme
Imagine a fictional provider selling a programme that brings performance insight, risk monitoring and implementation planning together. The offer includes a diagnostic phase, prioritised actions, a narrow pilot and a later decision about broader adoption. This is an invented illustration of the sales process, not a real Neurofactor study, customer case or measured performance improvement.
To the CEO, the provider starts with strategy, organisational ownership, board visibility and how downside risks will be monitored. To the owner-director, the provider starts with a value hypothesis: what costs and exposures should be investigated, what is the maximum fee, how will potential gains be assessed and how can the existing accountant contribute? Same scope. Different order of proof.
The pitch and business case should change order, not facts
For a CEO, open with the strategic problem in one sentence. Then explain delivery and reputational implications, board-level references, governance and only then the operational mechanism. Be explicit about assumptions the board must approve and circumstances under which the plan should stop or be revised.
For a DGA, start with the value that could be protected or created, the cost of the engagement and the downside risk. Follow with comparable owner-managed cases, pricing and a clear division of work with existing advisers. Both versions must be grounded in the same honest facts. No business case should exaggerate savings, returns or certainty to suit a presumed psychological preference.
A demonstration should help each person make their own decision
A CEO may prefer a structured view of how strategic intent becomes execution: who has responsibility, which decisions come to the executive team and how potential implementation failures are escalated. Demonstrate management control without implying that a single dashboard captures every reality inside an organisation.
For a DGA, a transparent diagnostic example can be more persuasive: key assumptions, cost categories, uncertain outcomes and the boundaries of advice. A small, defined engagement can test whether the larger programme is warranted. Agree beforehand which results would justify proceeding. A pilot is not proof of success until its measurements and limitations are clear.
Contact routes are part of the credibility story
The CEO card prefers an introduction through a supervisory board member, fellow CEO or trusted adviser, followed by a personal meeting. LinkedIn is more often a professional platform and news source than a place for active replies. A relevant, concise approach involving senior expertise is likely to fit this source profile better than a generic sequence of automated messages.
The DGA card points to introductions by accountants or advisers, followed by a private substantive conversation. LinkedIn use is selective, alongside professional media and a personal advisory network. A thoughtful follow-up addresses the specific value question, scope, fees and how existing advisers can remain involved.
Six questions to ask before the next sales presentation
Who formally approves the decision? Who can block it? Which negative outcome would matter most to this particular decision maker? What strategic or financial result must be made testable? Which proof would count as credible in this company? And whose introduction is trusted? The answers should shape the opening of the conversation.
Prepare two documents from one evidence base: a board-oriented memo covering strategic impact, governance, reputation and execution risk, and an owner-oriented view covering enterprise value, expenditure, uncertainty, advisers and contractual limits. Make the assumptions visible in both. This is relevance, not a different version of the truth.
What the profiles establish and what still requires research
These are broad, evidence-informed function profiles based on recurring patterns in years of Neurofactor research involving these and comparable audiences. Each profile includes forty categories, including motives, problems, objections, proof needs, contact preferences and BIS/BAS/k. The scores are not individual assessments, representative population averages or causal evidence that ownership alone determines a decision.
Sector, organisation size, ticket value, shareholding, supplier history and the current decision all matter. Build a proposition-specific target-group profile and an association map to examine what value, safety and risk evoke in your market. See selling to executives, selling to entrepreneurs and founder versus DGA for adjacent perspectives. Contextual verification matters more than applying a score mechanically.
Key terms
- CEO
- Chief Executive Officer, the executive accountable for a company’s direction, outcomes and reputation.
- DGA
- Dutch abbreviation for director-major shareholder, combining management authority with a substantial ownership stake.
- BIS
- Behavioral Inhibition System, a concept concerning sensitivity to potential threat or negative outcomes.
- BAS
- Behavioral Activation System, a concept concerning the pursuit of potential rewards and opportunities.
- k value
- A delay-discounting parameter that is separate from BIS/BAS and does not represent purchase likelihood.
- Corporate governance
- The arrangements by which decisions are made, overseen and accounted for.
- Reputational risk
- The possibility that an action damages confidence in an executive or organisation.
- Enterprise value
- An assessment of the economic value of a business, dependent on assumptions and methodology.
- Board memo
- A concise decision paper outlining strategic objectives, options, risks and accountability.
- Track record
- Documented, relevant experience and outcomes from comparable work.
- Association map
- A research-based view of the meanings and associations a target group links to a proposition.
Frequently asked questions
How do a CEO and a Dutch DGA differ as buyers?
The CEO profile emphasises organisational strategy, board accountability and reputation. The DGA profile additionally emphasises ownership value, wealth exposure and cooperation with established advisers. Real buyers can combine these concerns.
Does a DGA have a higher BIS score than a CEO?
In these broad Neurofactor profiles, the CEO is BIS 6 and the DGA BIS 7. This is a directional profile comparison, not an individual test result or representative average.
Does the identical k value mean they decide at the same speed?
No. Both cards show k 0.10, but k is a separate delay-discounting indicator, not a forecast of sales-cycle duration or the chance of buying.
What proof does the CEO profile prefer?
Recognised organisational references, senior counterparts and a verifiable board-level track record linked to strategy and implementation.
Which evidence matters to the owner-director?
Numerical analysis, experience with comparable companies, clear deliverables, transparent fees and a precise complement to existing accountants or advisers.
How do I pitch one offer to both executives?
Keep the facts and uncertainties consistent. Start with strategy, governance and reputation for the CEO, and enterprise value, costs, downside protection and adviser fit for the DGA. Test assumptions with a market-specific target-group profile.
Sources
- 1.>5 years of Neurofactor target group research - Neurofactor
- 2.Carver & White (1994), Behavioral Inhibition, Behavioral Activation, and Affective Responses to Impending Reward and Punishment - Journal of Personality and Social Psychology (1994)
- 3.Frederick, Loewenstein & O'Donoghue (2002), Time Discounting and Time Preference: A Critical Review - Journal of Economic Literature (2002)
This series
Who are you really selling to?Category synthesis
36 roles, four decision patterns: what job titles hide about B2B buyersRead next
Related topics
Reviewed by: Martijn den Otter · Last reviewed: 10/11/2026
Martijn den Otter
Oprichter van Neurofactor. Expert in neuromarketing en consumentenpsychologie.
LinkedIn →